Homeowners Insurance Designed Around
Your Home & Lifestyle
Personalized Coverage Designed to Protect
What Matters Most Today and As Your Needs Evolve
Your home is more than a property. It’s where daily life happens, where memories are made, and where long-term investments take shape. At HomePoint Insurance, we help homeowners secure coverage that protects their home, belongings, and financial well-being. We take the time to understand your property, location, and goals so your coverage fits your needs today, and adapts as those needs evolve.
Coverage tailored to your home & location
Personalized homeowners insurance designed around your property, location, and the way you live.
Access to top-rated national & regional carriers
We partner with trusted national and regional insurance carriers to help you compare quality coverage options.
Support aligned with your homeownership journey
Whether you’re buying your first home, relocating, renovating, or reviewing your coverage, we’re here to help protect what matters most.
Nationwide service with local expertise
Receive personalized guidance from experienced insurance professionals backed by the resources of a nationwide agency.
Understanding Homeowners Insurance
Homeowners insurance is designed to protect more than just your property. It provides financial protection for your home’s structure, your belongings, liability exposure, and additional living expenses if your home becomes uninhabitable due to a covered loss. Coverage is tailored based on your home, location, and individual risk factors, making it important to review options carefully before selecting a policy.
Homeowners Insurance Explained
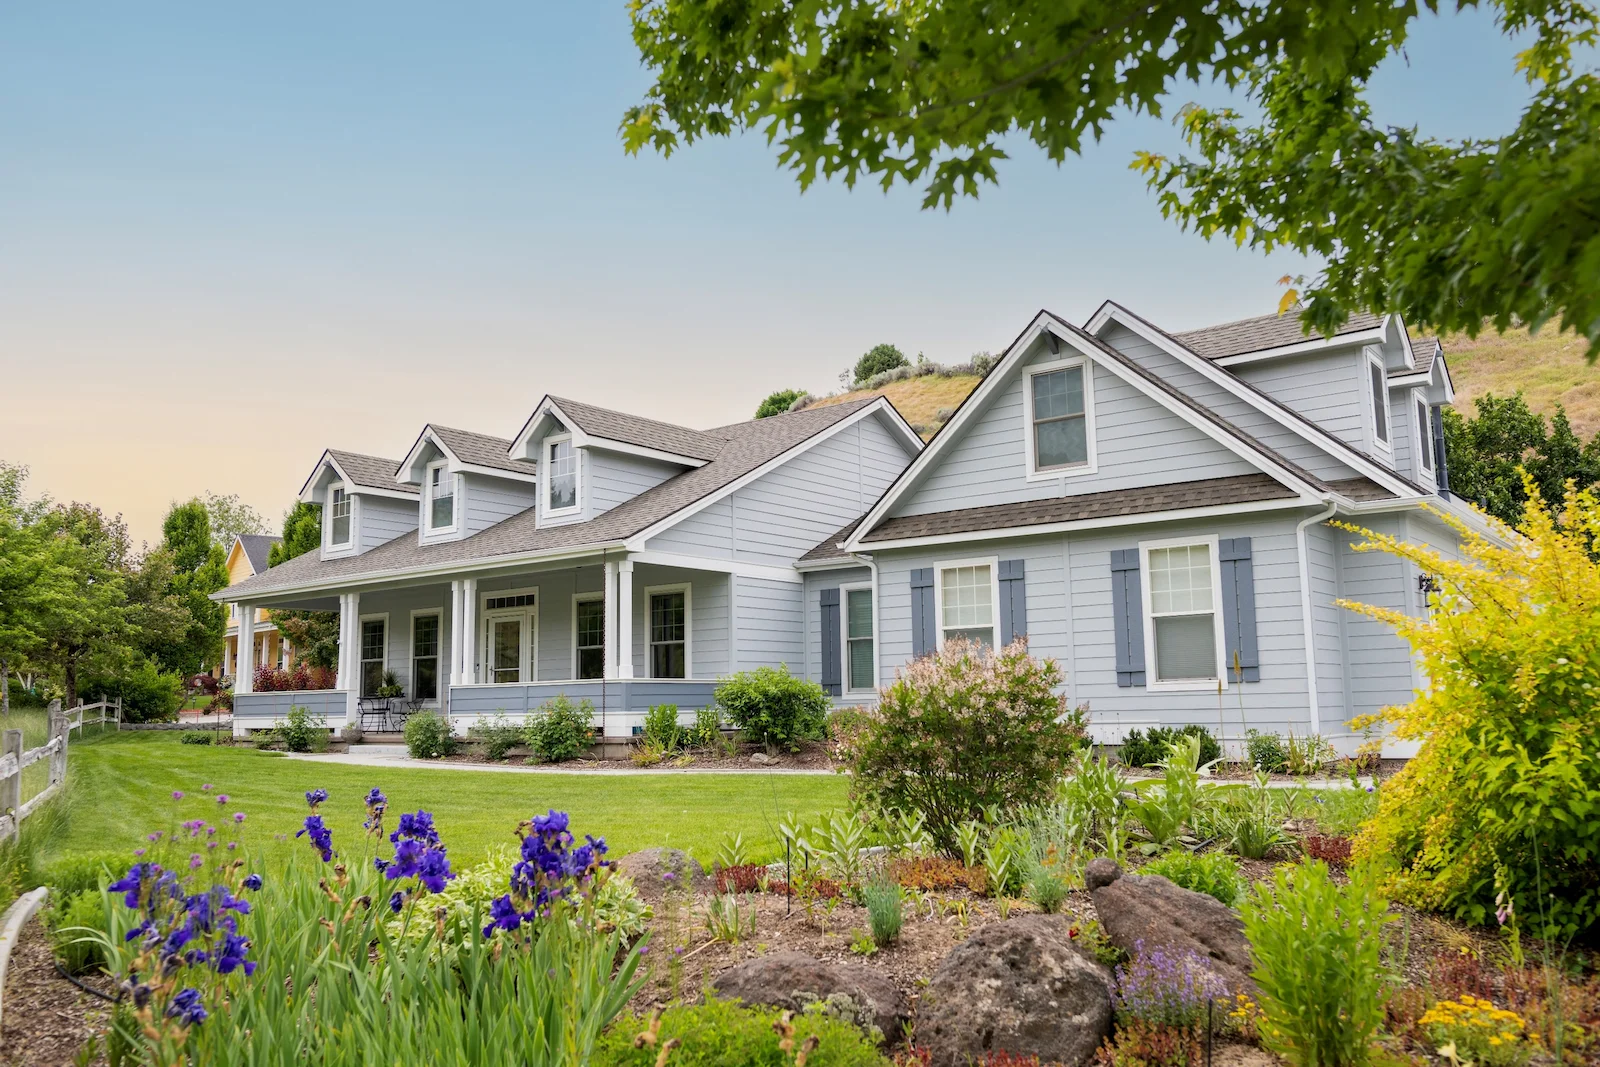
Dwelling
Protection for the structure of your home.
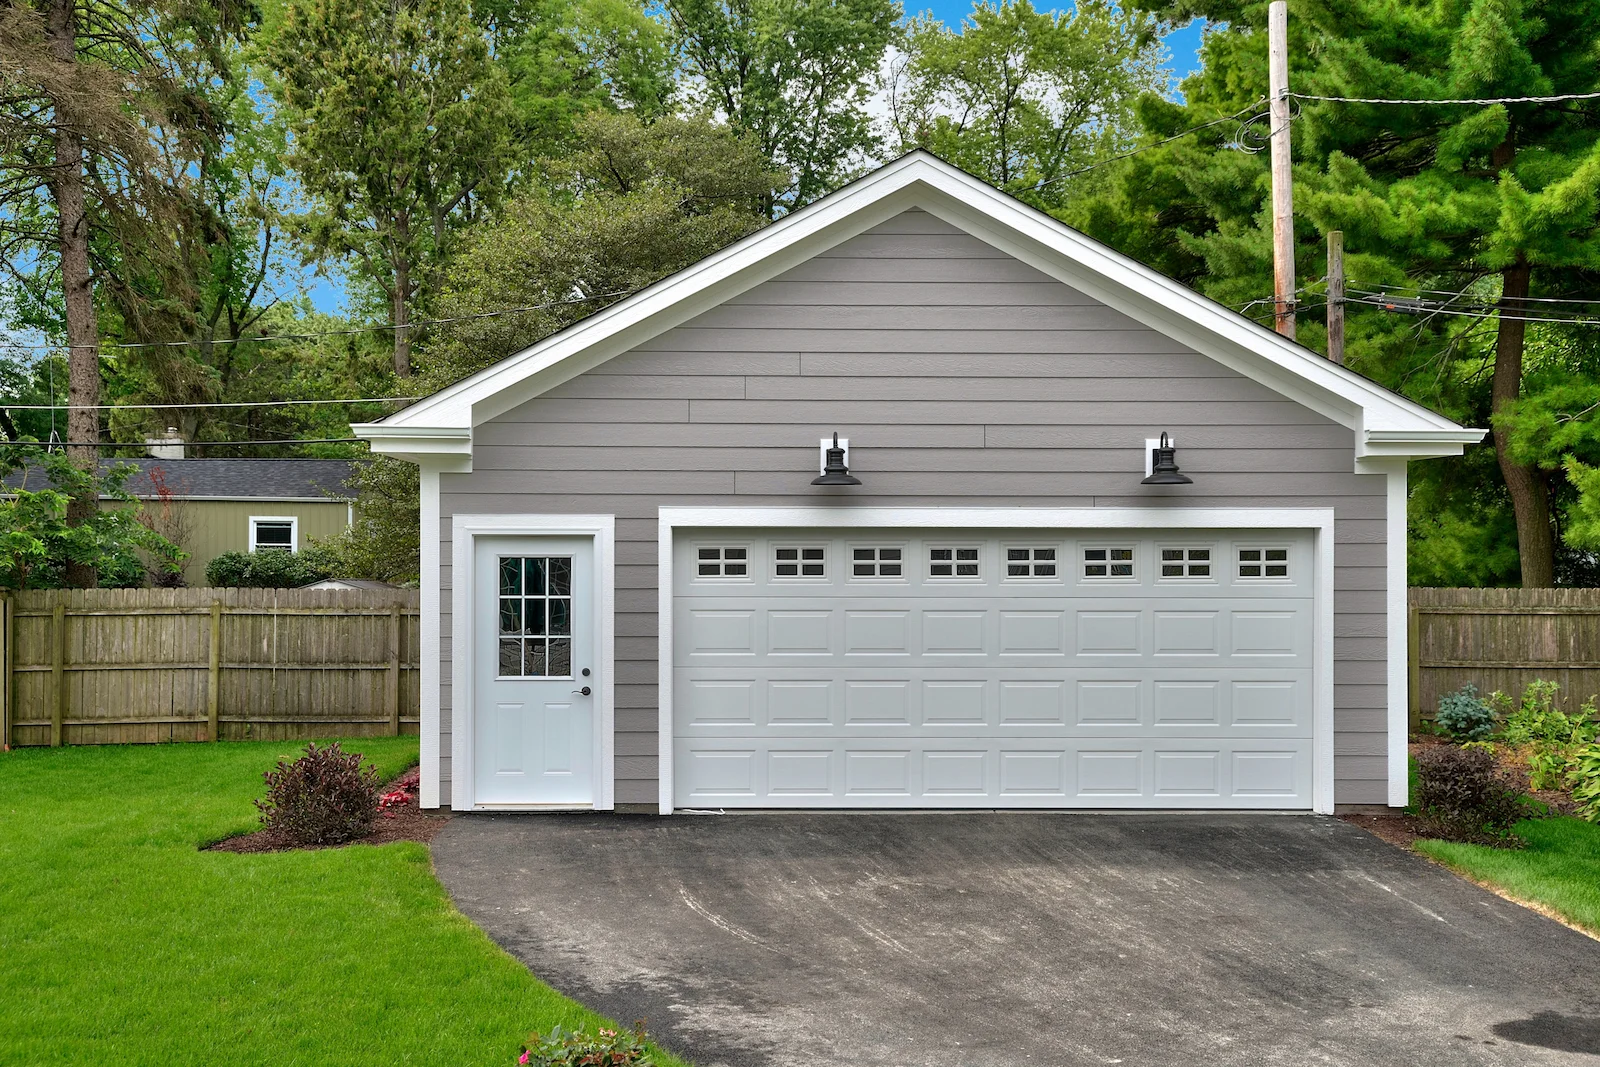
Other Structures
Coverage for garages, sheds, and fences.
Personal Property
Coverage for belongings inside the home.
Liability
Protection if someone is injured on your property.
Loss of Use
Help with temporary living expenses after a covered loss.
Why Homeowners Choose HomePoint Insurance
Personalized Coverage
Coverage designed around your home, location and the way you live.
Multiple Carrier Options
Access to trusted national and regional insurance carriers.
Experienced Guidance
Helping you understand your coverage options and make informed decisions.
Ongoing Support
Helping review your coverage as your home and insurance needs evolve.
Homeownership Support
We help coordinate coverage for home purchases, refinances, and policy updates.
Coverage Designed Around Your Individual Needs
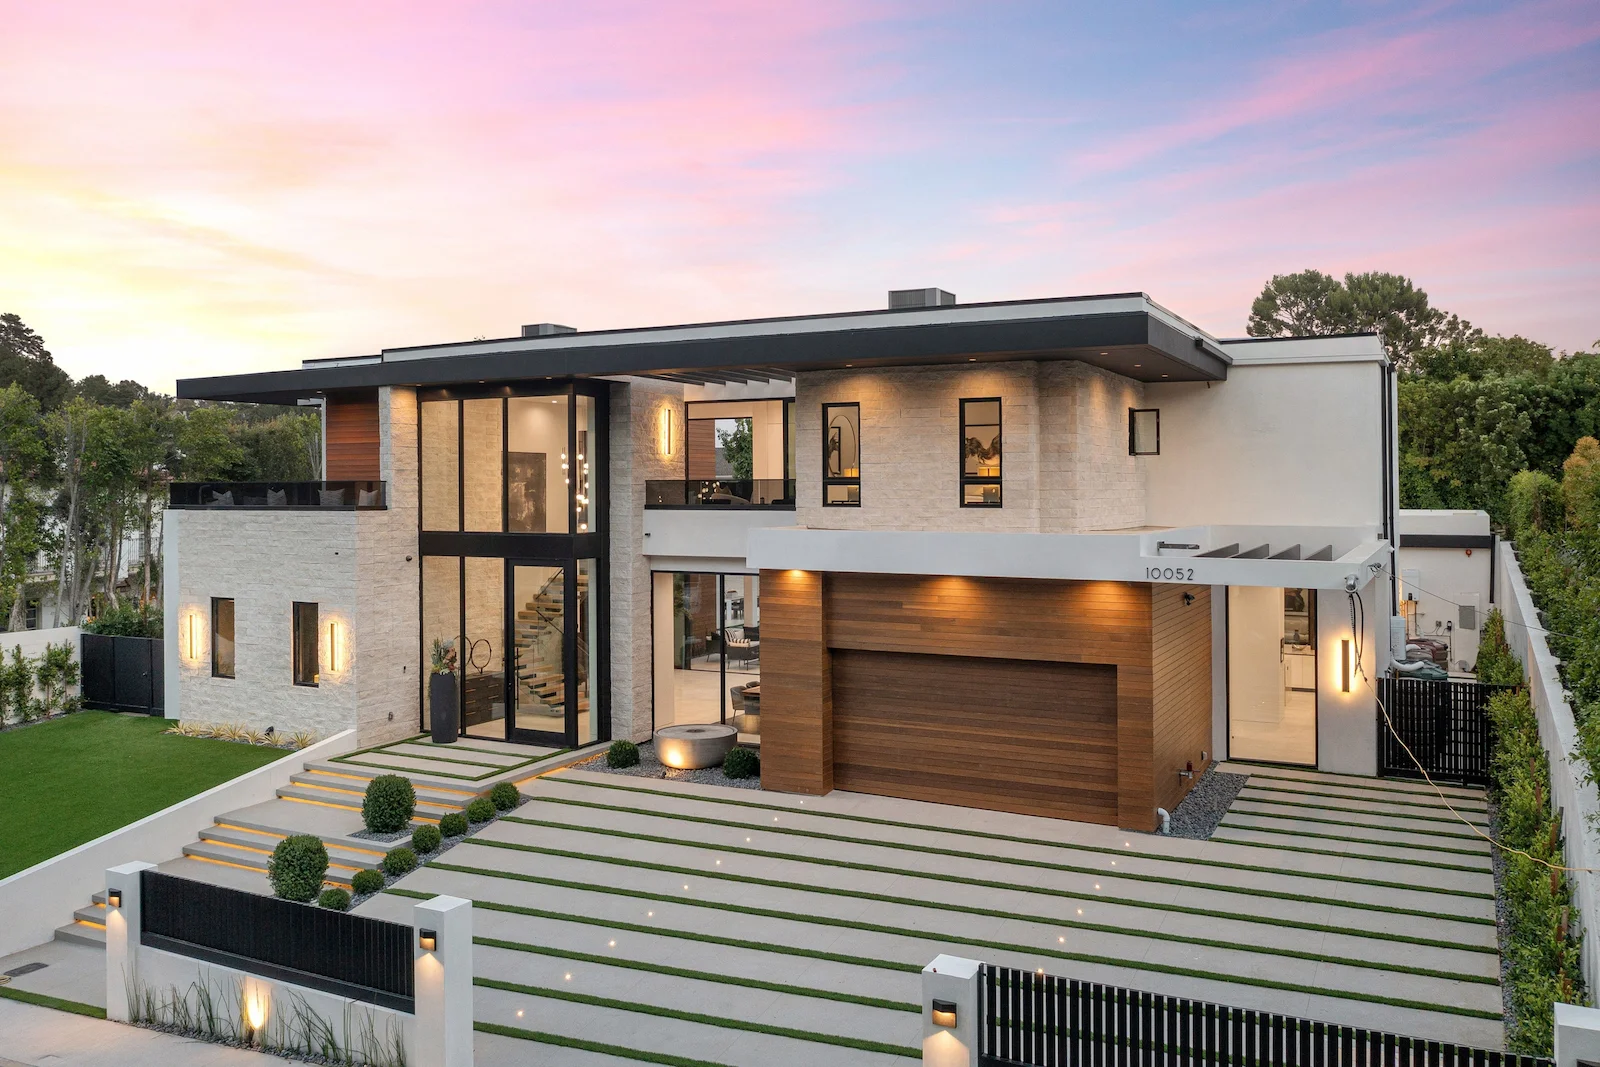
High-Value or Custom Homes
Specialized coverage designed for higher replacement costs, custom features, and expanded protection needs.
Condo or Townhome Owners
Coverage designed to complement your associations’ master policy, focusing on interior protection, personal property, and liability.
First-Time Homebuyers
Coverage the meets lender requirements while protecting your home and belongings, without unnecessary complexity.
Seasonal or Secondary Residences
Coverage built for part-time occupancy, location-specific risks, and year-round protection.
Builder’s Risk (Homes Under Construction)
Coverage designed for home being built or renovated, protecting materials, structure, and certain risks during the construction phase.
Explore Our Other Insurance Lines of Business
Protect your pet with insurance that helps cover unexpected vet bills — so you can focus on care, not costs.
It is important that you have liability protection and coverage for damage to your vehicle in the event you are in an accident.
Umbrella liability insurance takes over where your home and auto insurance leave off.
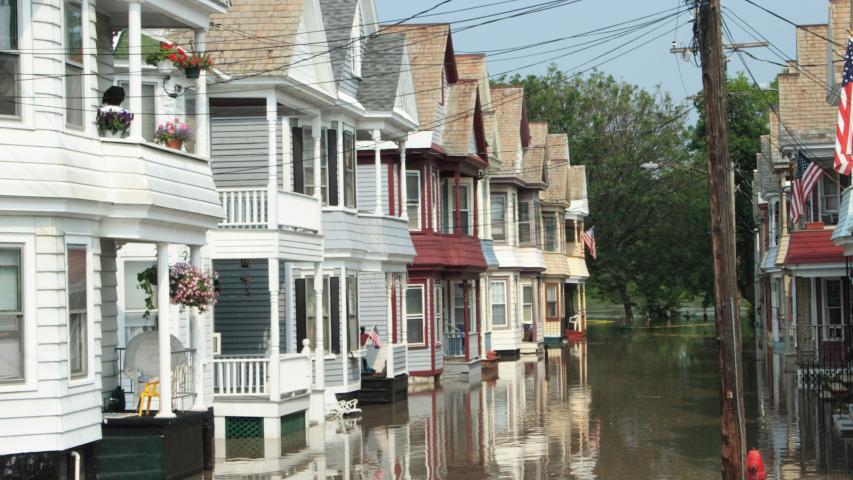
Flood damage is not typically covered by a homeowner’s insurance policy. 20% of Flood claims are within low risk areas.
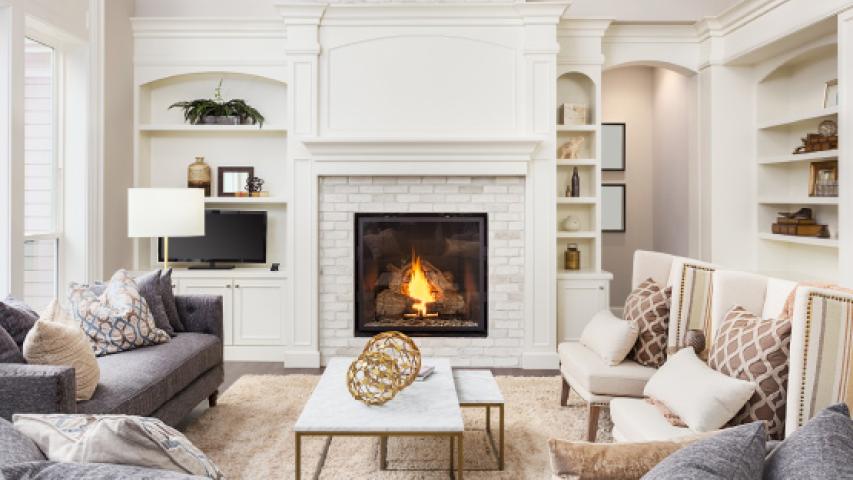
While a landlord’s insurance typically covers structural damage, it won’t protect your personal property from fire, theft and other disaster.
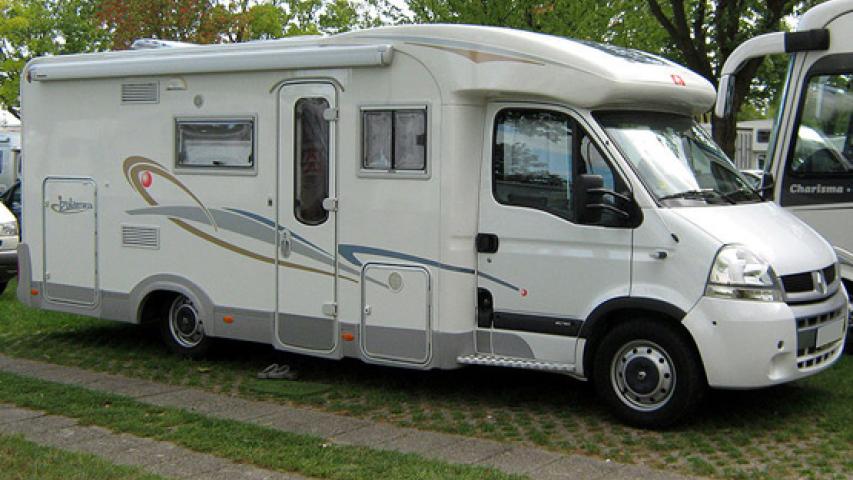
A recreational vehicle faces the same dangers on the road as an auto and it requires special insurance.
Protect Your Home with Confidence
Whether you’re purchasing a new home or reviewing existing coverage, our team is here to help you explore options and build protection that fits your needs. At HomePoint Insurance, we’ll help you compare vehicle insurance options so you can enjoy your home with confidence, knowing you’re prepared for life’s unexpected moments.
Coverage subject to policy terms and conditions
Homeowners Insurance FAQs
Homeowners insurance generally includes protection for your home’s structure, personal belongings, liability, and additional living expenses if your home becomes uninhabitable due to a covered loss.
Insurance is based on the cost to rebuild your home, not its market value. Land value and market conditions are not included in replacement cost calculations.
Quotes are based on initial information. As additional details are verified, such as property characteristics or underwriting requirements, pricing or coverage may be adjusted.
No. Standard homeowners policies typically do not cover flood damage. Separate flood insurance may be required depending on your location.
You may be able to lower your homeowners insurance premium by increasing your deductible, maintaining a strong claims history, installing safety or security features, and bundling your homeowners policy with auto or other insurance policies. Bundling can offer added convenience and may result in potential savings.
Certain items like jewelry, art, or collectibles may require additional coverage or endorsements beyond standard policy limits.
If your home is vacant for a period specified in your policy, coverage may be significantly restricted. Certain types of losses may not be covered while a home is vacant.